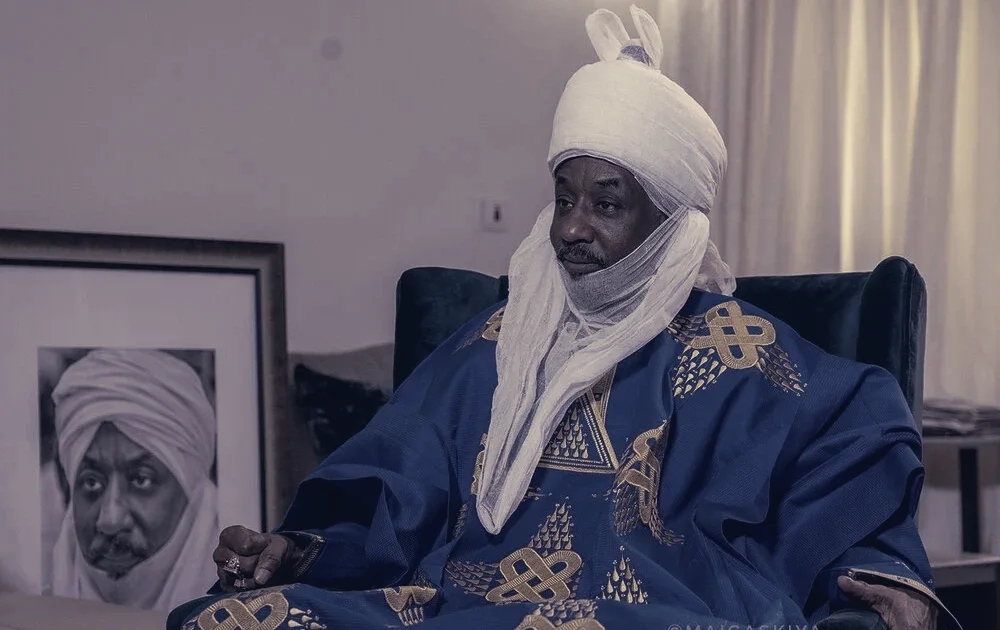
Nigeria’s progress on bringing citizens into the formal financial system lost pace, Muhammadu Sanusi II said, after he delayed telecommunications companies from offering banking services during his tenure at the Central Bank of Nigeria. The former governor framed the decision as a mistake at a fireside chat held in Abuja to mark the launch of the Access to Financial Services in Nigeria 2026 Survey Report.
Sanusi, who is now the Emir of Kano and led the CBN from 2009 to 2014, said worries about the safety of depositors after a banking crisis informed his resistance to allowing nonbank firms access to large pools of funds. “I’m responsible for delaying the entry of telcos into this space,” he told the audience. He recalled pushing back against international and domestic voices urging a faster opening of the sector. “I fought the World Bank. I fought everybody,” he said.
He said that, with hindsight, the policy slowed efforts to reach the unbanked and underbanked. Sanusi argued that the expansion of technology-enabled financial services in recent years has shown the limits of relying mainly on traditional banks, which lack the retail footprint to reach many communities. The survey presented at the event found overall financial inclusion at 79% in 2026, the financially excluded share at 21%, and formal financial inclusion at 73%, up from 64% in 2023.
Sanusi cautioned that opening accounts and enabling digital payments does not by itself raise incomes or solve poverty. He urged that financial access be tied to productive activities across agriculture, manufacturing and trade so that finance supports real economic activity. He urged regulators and industry players to use existing digital payments networks to broaden access to savings, pensions and insurance.
Outlining a practical step, Sanusi said he would convene major digital financial providers and challenge them to design pension and savings products that tap transaction data and everyday payment flows. He proposed mechanisms that would allow small sums to accumulate from routine transactions, creating saving and risk buffers for informal workers who cannot make large periodic contributions.
He also pressed the central bank to keep price stability a priority, describing inflation as the greatest threat to household savings and wealth and warning against prematurely loosening tight monetary policy. Sanusi pointed to recent investments in a unified identification and payments infrastructure as a platform to build credit, insurance and pension services, and he warned against fragmented consumer protection rules that could undermine those gains. His remarks leave open a policy question for regulators and digital providers on how to convert expanded access into durable economic opportunity.